 01
 02
 03
 04
 05
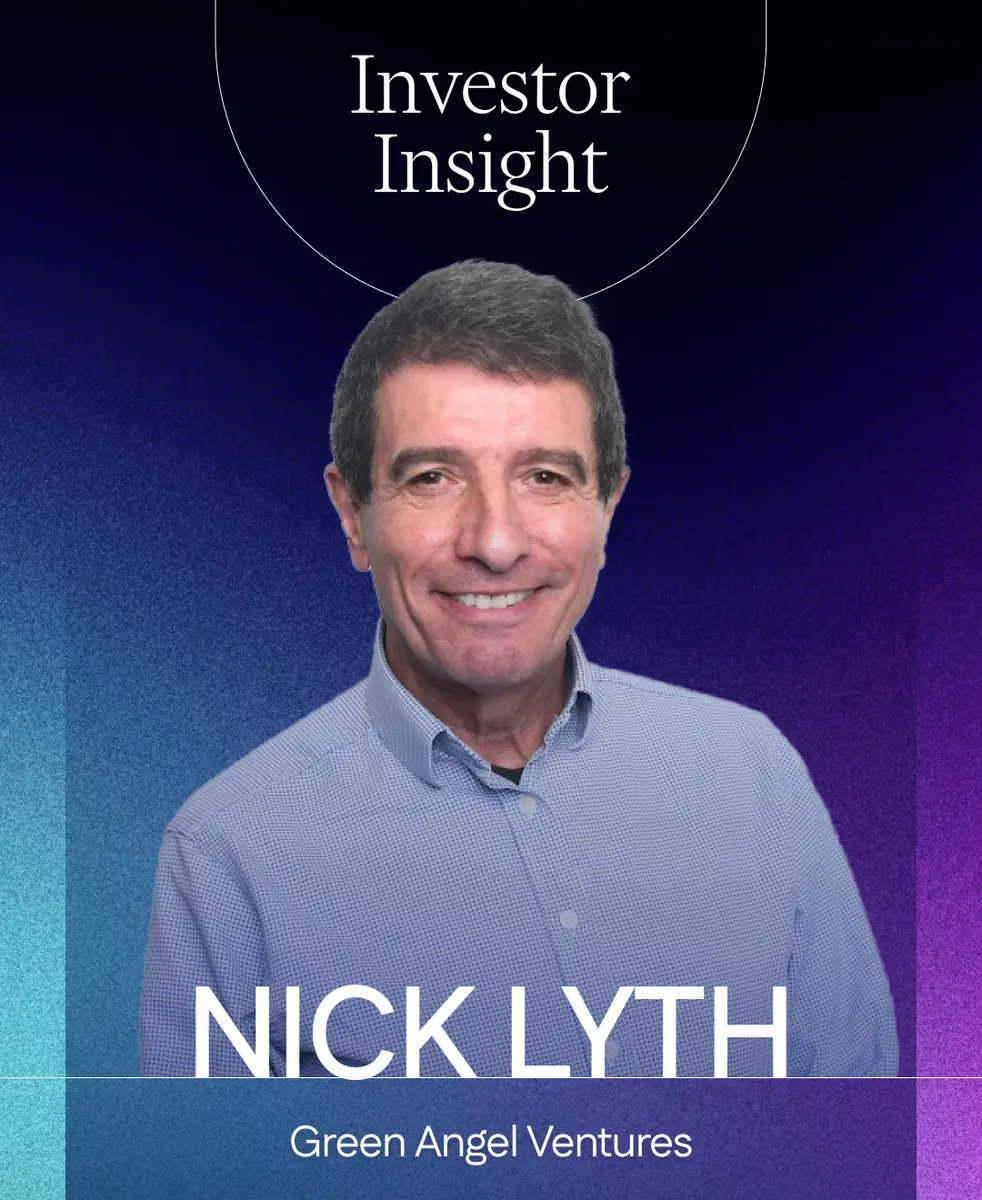
Brighter Future editorial analysis · 27th September 2026
What this interview reveals
One test before the usual ones
Green Angel Ventures has a single entry test. “Our unique criterion is the ability to reduce carbon emissions.” A company that passes then faces the standard early-stage review of technology, IP, team, traction and financial projections. The syndicate invests only where it has inside knowledge, including energy, water, food and agriculture, waste and the built environment. Lyth singles out residential heating as the UK's biggest carbon emitter and one that draws far less investment than renewables and electric vehicles. When war, inflation and UK political leaders qualifying their net zero commitments sent other investors back to lower-risk areas, the syndicate kept its criteria unchanged.
Sell the better carriage
Lyth distrusts first movers and talk of disruption. He points to the car, sold as a horseless carriage, to argue that people accept change when it arrives as a better version of something they already buy. “The core concept is improvement, not disruption or problem-solving.” A small company rarely has the resources to create demand from nothing, so he tells founders to enter a market where people already spend money and to think of themselves as competitors.
What ends a deal
The red flags are about people. Arrogant or unresponsive founders, claims that fail due diligence and single founders with autocratic tendencies end the conversation, and the syndicate prefers teams of two or more. Its diligence covers 14 to 15 areas with a traffic-light rating and takes at least six weeks, so founders who need speed are told to look elsewhere. Lyth calls good ideas cheap. The hard part is selling in volume at a price that builds a business. His own example of the payoff is Nature Metrics, which measures biodiversity from environmental DNA. By his account, the syndicate invested at a valuation of about £3 or £4 million, and by 2024 the company was approaching £50 million.
What we would carry into the brand
For a founder approaching this syndicate, the first line should state the emissions cut. The next should place the product in a market that already pays for the older version, with the proof of improvement up front. We would describe the company as the better carriage, leave the word disruption out of the deck and plan the raise around at least six weeks of diligence. Lyth puts the syndicate's record, by his count 44 investments and one failure, down to specialisation, and he credits the same focus for its growth.
Our concrete mission drove continued growth while others suffered from vagueness around "the environment" generally. - Exact excerpt from the historical interview
The conversation
Historical investor interview: originally published 23rd of May 2024. The historical interview feature below is preserved verbatim. Roles, fund details and affiliations reflect the publication date unless a later update is explicitly labelled.
Thank you so much for being here, Nick. Do you think you could give me a brief introduction to yourself and your company?
I'm Nick Lyth, founder of Green Angel Ventures— the UK's only angel investment syndicate specialising in fighting climate change. We focus on energy, food/agriculture, water, the built environment, waste and recycling sectors where we have expertise.
Our track record is unique— 44 investments with only 1 failure. We invest solely in innovations that, once commercialised, will reduce carbon emissions. Addressing climate change is highly important, as 14 of the 17 UN Sustainable Development Goals depend on solving it first.
Green Angel Ventures is now one of the largest UK angel syndicates with over 300 members. We've launched a fund alongside the syndicate, both focused on climate change solutions. We're purpose-driven— making money is the byproduct, not the goal.
We welcome anyone interested in joining our mission, within financial eligibility constraints. Our purpose is to fight climate change through investment. If we're successful, as we must be because climate change isn't waiting, you will make money, but that's not our primary aim. We're using investment and commercial opportunities to make the fight against climate change more effective.

Congratulations on your success, and thank you for spelling out what you do so clearly. Could you please share your investment focus areas for the current year and the rationale behind them?
Our core focus is investing in innovations that reduce carbon emissions, especially in energy, water, food/agriculture, the built environment, waste/recycling, and transport like electric vehicles/bikes.
We don’t look at sectors in which we have no inside knowledge. For example, sustainable aviation fuel is very important, but we lack expertise there currently. Ironically, synthetic aviation fuels have been familiar territory for years. Similarly, wind energy technology, one of our specialist sectors, was known for over 120 years. Both have been overlooked until recently for economic reasons. They were discarded as being unaffordable, compared to fossil fuel-based options.
Most climate tech investment goes to renewable energy and electric vehicles, neglecting other key areas. The built environment— heating, ventilation, insulation— gets far less attention despite residential heating being the biggest UK carbon emitter.
The government promotes air source heat pumps, but we're unsure if they're truly suitable yet due to high costs and need for extensive home retrofitting.
Our focus areas evolve yearly based on emerging priorities in fighting climate change, while maintaining our core mission of reducing emissions through investable innovations.
In light of recent global economic changes, how have your investment criteria evolved?
The direct answer to your question is that our criteria haven't changed. Over the last decade, interest in climate investing has gradually accelerated. Initially, we were the UK's only angel syndicate specialising in this area. Many have since copied us, including larger investment organisations.
Broader interest in climate investing has fluctuated. ESG investing emerged, though its complexity blurred its impact. The UN Sustainable Development Goals and "impact investing" provided some focus.
The pandemic increased climate investment, highlighting shared vulnerabilities and prompting reflection. Green Angel Ventures doubled in size during this period.
COP26 in Glasgow further boosted interest. However, recent geopolitics like the Ukraine war, war in Gaza, and inflation have deprioritised climate for many investors.
Leaders including both Rishi Sunak and Keir Starmer made net zero commitments but last year qualified them and prioritised energy access over renewable sources temporarily. This caused some investors to lose interest in climate change, reverting to familiar lower-risk areas.
For us, this intensified our specific climate change/emissions focus— still seen as very important despite broader deprioritisation. Our concrete mission drove continued growth while others suffered from vagueness around "the environment" generally.

The recent shift backward due to geopolitical instability is fascinating and a little horrifying; thank you. For my next question, what would you say are the key qualities that Green Angel Ventures looks for when investing in a startup?
Our unique criterion is the ability to reduce carbon emissions. If you don't meet this, you're out. Once we're certain you meet it, we assess all the standard early-stage investment criteria:
Technology, intellectual property, the team, traction with potential customers, and financial projections. These are all the elements you'd expect any investor in early-stage companies to evaluate.
Essentially, the unique one is the ability to reduce carbon emissions. That's something nobody else will be looking for, but we are, and if you don't meet that criterion, you're out. Once we are certain that you meet that criterion, everything else is exactly as you would expect from any investor in early-stage companies: the technology, the intellectual property, traction with potential customers, market research that shows your market appeal, and your financial projections. All the things you would expect
What founder or startup traits would lead you to say no immediately?
Key traits leading to investment rejection: unresponsive or arrogant founders unwilling to take advice; exaggerated claims not holding up to due diligence; single founders with autocratic tendencies— we prefer teams of 2+ for checks and balances; mismatched fundraising goals and financial plans.
We may allow exceptions on fundraising if founders can revise plans convincingly for a reduced amount. But founder quality and openness to guidance are very important— red flags here are immediate dealbreakers.
Often, problems in intellectual property, technology, or competitive assessment trace back to the founders or leaders. Ultimately, that's what it always comes down to.
That’s very interesting— thank you. I wanted to ask about the due diligence process you mentioned: how do you do that before you go about making an investment?
Our due diligence process for angel investments is systematised and award-winning, unusual for angel syndicates. It covers 14-15 areas including technology, IP, competition, customer traction, market research, financials, and team— each with specific questions.
We record all questions and company answers for members to review and add queries. Our traffic light rating system fails companies with unresolvable "red" flags after thorough examination. This structured approach provides rigour.
For larger funds assessing mature companies, professional due diligence is far more complex because there is so much more to examine. Our process, however, is tailored effectively for angel investments while exceeding typical angel norms.

How do you evaluate the potential of a company in its early stages?
There's no scientific method for early-stage investment, which is why it's high risk. Over 90% of startups fail in their first year, and 90% of those remaining fail in their second. Nobody intends to fail— they've miscalculated or been surprised, and of course, so have their investors.
Our record comfortably beats that— only one company in our portfolio has failed. However, this is not a matter of luck. It’s a consequence of our specialisation. We’re specialists who know what we're doing.
Still, I'd say there's no science to it— there's conviction. We invest where we're convinced. Every startup claims they'll succeed and grow, so we look past that. We invest in those we're genuinely convinced by, in markets we know and understand.
How do you balance the need for quick decisions in competitive deals with your evaluation?
We don't. If there's a need for speed, we nearly always tell them to look for funding somewhere else. We are not going to cut corners. This process will take at least six weeks and maybe closer to two to three months if we are doing it quickly. Conventionally, the industry allows 6-9 months, and we are no different in that respect.
Can you share an example of a successful investment that you made and what made it stand out?
There's a company called Nature Metrics which has developed software for measuring DNA in a land mass. By analysing the DNA found in the environment, they can provide accurate data on the animal and plant life populations in that area, in other words the Biodiversity. No-one else can do that, it radically revises the time and cost of producing this essential data.
That’s incredible.
It's very clever indeed, and has grown and grown. We invested at a valuation of about £3 or £4 million. It's now approaching £50 million and still growing. It's enormously useful in both commercial and public sectors, including organisations like the World Conservation Monitoring Centre —the UN body responsible for all biodiversity data. It's used in various contexts, and there's no competition. For us, it's one of our highlights— a poster child and a wonderful story.
Yes, I am extremely impressed with that. To measure animal and plant populations with environmental DNA makes sense in the science, but it’s still like magic. For our next question, I just wanted to ask: in your experience, what are the most common reasons that startups fail after receiving an investment? And how can this be mitigated?
This is a question I've never been asked before. I'd be very interested to ask some of my colleagues. My personal answer is myopic management— a CEO who won’t listen, in other words.
How important is the scalability of a startup's business model in your investment decision?
Yeah, it's a very simple answer: it has to be scalable. If it's not scalable, you're not investing in a real business.
Can you share insights on the importance of diversity and inclusion in the teams you invest in?
Diversity is very important, and research shows companies with more diverse boards are more successful. Less diverse boards tend to be less successful.
The reason for diversity is to avoid your board becoming an echo chamber. If everyone thinks the same, board meetings are essentially a waste of time— you could have them with just one person. You need different perspectives that bring challenges.
That's why diversity is so important. It's not just about the principle of equality and giving everyone a chance; it's about efficient and effective management.
What role does mentorship play in your investment strategy and how do you support your portfolio companies?
You want to do everything possible to help a company succeed. Effective interventions are very important. It's all about the quality of the intervention. If it's low quality, you're not helping; you're wasting their time and your own.
Mentorship often involves putting someone on the board. This person acts as a director and must act in the company's best interests, not the investor's. This position and contribution are very important.
However, mentorship as it's often practised can be a waste of time— self-aggrandisement for old men telling entrepreneurs what to do, which they often ignore. Sometimes it works, but it's not calibrated to have any real effect.
How do you view competition in the startups you invest in? Do you prefer first movers or better movers?
First movers are often on treacherous ground, and equally, they often don't realise it. You want your companies to be developing an innovation, a new technology, or a new process for a market which already exists. A lot of nonsense is talked about disruption, innovation and problem-solving. All that stuff about disruption? Human beings are change-averse— they don't like disruption, it's not a good thing.
Consider what was probably the most disruptive technology in the last 150 years, contrary to popular opinion about recent changes in the last 20 years. What was enormously more disruptive was the invention of the car, and it was resisted hugely. This is a question for you: why is the car called the car?
It's short for "carriage", as in “horse and carriage”.
It's a horseless carriage— an improvement, not a disruption. They said, "We're doing the same thing, only better. It's your carriage, just horseless." This encouraged acceptance.
The core concept is improvement, not disruption or problem-solving. It's entering an existing market with a better product. The key is making things better.
Being a "first mover" is risky. Instead, think of yourself as entering a market where people already spend money. That's very important. As a small company with limited resources, it's challenging to create demand for something entirely new.
When launching a horseless carriage, you approach carriage sellers saying, "You sell many carriages. I've got a better one— it's horseless." They'll be sceptical until you demonstrate it.
Don't aim to be a first mover. Change your mindset— think of yourself as a competitor, not an innovator.
That’s a fascinating example; thank you very much for that. What advice would you give to a startup seeking investment in the current market?
It's tough, regardless of market conditions. Assume it will take time. Expect a high failure rate— you might need 100 approaches for one investor. If lucky, maybe 50 approaches. If very lucky, perhaps 20, but better odds are unlikely.
Yes, that sounds about right. What are the emerging technologies or sectors that you believe are under-invested and why?
For climate change, renewable energy and electric vehicles have thrived due to government subsidies and regulations. These areas attracted investment because of clear reward opportunities.
Other areas like domestic heating, hydrogen use, and agriculture have been under-resourced. They're only now gaining investor attention. Innovations in these sectors are emerging, but it's quite late— it's unfortunate this didn't happen sooner.
How do you see the investment landscape evolving in the next few years?
The investment landscape deteriorated in 2023, with no clear signs of improvement in 2024. Our main concern is the geopolitical situation— the wars in Ukraine and Gaza, and fears of wider conflict. This, combined with inflation and interest rate hikes, has caused significant unease.
Energy security has become a top priority, largely due to the Ukraine war. It's difficult to predict when investment will recover. 2024 will likely remain challenging, and if geopolitical circumstances worsen, investments may become even tougher.
This is a somewhat gloomy outlook, but it's a complex issue with no definitive answer.

What is one thing people believe about investing that is completely wrong?
All early-stage investors should understand they may lose everything. Those who don't are unwise— it's very high-risk. Many startups, especially early-stage ones, fail. We invest in pre-revenue companies that aren't even trading yet. These aren't wise investments in the traditional sense. Keep this in mind if you want to try out the startup investment world.
Which is more important, a great idea or a great team?
A great team is more important. I often upset companies by saying that good ideas are two a penny— that's the easy part. The challenge is selling in volume at a high enough price to create a successful business. If you can't do that, your idea is worthless. If you can, the quality of your idea matters less.
There are many examples of subpar products achieving business success, while superior products struggle. It's because the successful team figured out how to sell, while others didn't.
It's always about the team, not just the ideas you're planning.
Which tech solution do you think is actually harming the planet more than helping?
I'm not fully convinced by electric vehicles. They use lots of lithium, and production is carbon-intensive. They don't reduce car volume on roads, which is problematic.
As an electric vehicle driver, I had good intentions. A month after getting one, I found a study comparing it to our previous petrol Citroën Berlingo— a functional, basic model we loved.
The study suggested driving internal combustion vehicles until they're unusable to reduce carbon emissions. Then consider an electric vehicle. It didn't say electric vehicles were bad, but emphasised using existing vehicles and discouraging new production.
That’s a very interesting perspective! Nick, this has been a fascinating and fun conversation. Thank you so much for giving us your time and thoughts, and from all of us at Brighter Future, we hope Green Angel Ventures continues to be as extremely successful as it’s already proven itself to be— and that the new venture fund you’re launching does incredibly well, too!
To learn more about Green Angel Ventures, please see their site at www.greenangelventures.com .
To learn more about their new Climate Venture Fund, please see www.greenangelventures.com/invest/climate-venture-fund .
Tell us what needs to move.
Bring the brief if it is clear. If it is unclear, tell us where the work is stuck.
Bring us the problem