 01
 02
 03
 04
 05
Sections
Picture a lender opening a deck and finding a slide headed “Project de-risked”. Underneath it are ten green ticks. Technology, feedstock, construction, offtake, regulation and financing all appear solved.
The slide is intended to create comfort, and it often creates the opposite response. A first-of-a-kind project exists because some important part of the commercial configuration has not been built before. If every uncertainty is shown as closed before construction, the reader has to decide whether the project is surprisingly ordinary or whether the presentation is hiding the hard parts. Anthony Chow, co-founder of the London-listed investment company Agronomics, put the investor's side of this plainly when we interviewed him in June 2024. “I don't like one-sided messaging where entrepreneurs completely disregard any risks or downside potential. For the most part, investors are not stupid, so treat them with respect and don't try to pull the wool over their eyes by glossing over obvious risks.” He was describing what he looks for at his own fund, and other investors weigh balance differently. A slide of ten green ticks is the kind of one-sided messaging he objects to. A stronger risk story gives uncertainty names, evidence states and owners so the reviewer can see the structure before evaluating the mitigation.
Separate the risks before describing the mitigations
A single project-risk score hides the information a serious reviewer needs. Technical performance, scale-up, construction, feedstock, product qualification, offtake, price, regulation, counterparty strength, operations, financing and schedule each have different evidence and different consequences.
Public finance for first commercial projects shows how much scrutiny remains at this stage. The US Department of Energy’s review of FOAK financing approaches describes long diligence periods before conditional commitments. That fact says nothing about whether better risk labels earn better terms.
The communication job is to arrive with the project already decomposed, so a reviewer does not have to discover the categories of uncertainty while also evaluating them. The first of those categories is often scale itself, which is why our FOAK guide opens on the question of the scale at which a claimed cost holds.
Give every major exposure an evidence state
A useful external risk register can distinguish six broad states without pretending they are a scoring system. Direct evidence comes from substantially the same configuration under relevant conditions. Smaller-scale evidence shows that something has been demonstrated and identifies the uncertainty introduced by scale. Transfer evidence comes from adjacent equipment, industries or project types and states where the comparison stops. Contractual allocation shows that a counterparty has accepted a defined obligation. Insurance or a guarantee changes a named financial consequence within the actual terms of the cover. Unresolved marks the exposure for which the project still lacks enough evidence or structure to make the uncertainty easy to price.
The boundary around each state does as much work as the label. “This compressor design has operated for five years in comparable temperature and pressure conditions” gives a reviewer something to test. “The plant is proven” makes a much larger claim on the same evidence.
The reviewer also arrives with a register of their own. Nick Lyth, founder of the UK angel syndicate Green Angel Ventures, described a diligence process covering 14 to 15 areas, from technology and IP to customer traction and financials, in a May 2024 interview. “Our traffic light rating system fails companies with unresolvable "red" flags after thorough examination.” That is one angel syndicate's process as he described it at the time. It shows why an all-green slide rarely survives review, because the reviewer will colour each exposure for themselves.
Mark every figure by its status
The same discipline applies to the numbers. At FOAK the project needs a concrete economic case, and many of its inputs still rest on engineering models, supplier quotations and scaled assumptions. Blending contracted and estimated figures into one confident total makes a lender discount all of them. Mark each line with one of four statuses instead. A contracted figure is fixed by a signed agreement, so the reader tests the counterparty and the terms. A quoted figure has been priced in writing by a supplier or contractor, so the reader checks the quote's date, scope and validity. A modelled figure comes from an engineering or financial model, so the reader reviews the model and its inputs. An assumed figure has been set by the team without a quote or a model, and the reader will ask what would turn it into a quote, a contract or data. The same marking applies to revenue, contingency and schedule, and it shows the team where the next piece of diligence work belongs.
Allocation changes who carries an event
A contract can materially improve a project without changing the underlying physical event, which is why the contractual obligation and the physical uncertainty need to stay separate in the risk account. If an engineering contractor accepts a completion obligation, construction delay can still happen. The contract changes who carries defined consequences. Insurance can cover a specified loss while the insured event remains possible. A guarantee can change the lender’s loss position without changing the technology. “De-risked” is often used for all three situations as though they were equivalent, and the party carrying the exposure sees materially different positions in each case. Engineering contractors are often asked to guarantee schedule, cost or performance for a configuration nobody has built. The developer has to say precisely what is novel, what is standard and which warranties and interfaces are realistic for a first build.
When an unresolved risk cannot be reduced before the next decision, the commercial structure may have to change. Capital can be released against milestones. A buyer can qualify a product before taking full volume. A guarantee can cover one narrow first-mover exposure. Engineering can progress before the notice to proceed, the formal instruction that starts full construction. These structures change a defined part of the exposure so a particular commitment can become possible under stated conditions, while the rest of the project remains available for separate evaluation.
Show the residual exposure and its owner
A useful risk row should tell the reader what can happen, what evidence exists, what has been done about it, who owns what remains, which condition would make the exposure unacceptable and what next evidence could reduce it. That structure also prevents the common slide in which ten risks each receive a reassuring mitigation sentence and nothing is left visibly unresolved.
Eeden, which turns textile waste into new raw materials for fibre, shows the same discipline on the buyer side. Its earlier deck for brands explained the technology and closed on contact details. In our account of that project, brand teams still carried questions about the chemicals in the process, the source of the material, the company’s ability to scale and who else was involved, and any one of them could stall a decision. We wrote personas for the people inside a brand who would sign, and their objections became the pitch’s frequently asked questions. The ask was then sized to the exposure that remained open. The pitch closed on a Letter of Intent that secures early access to pilot capacity and converts into a pilot contract.
Run the scale-up question through the fields of that row. What can happen is that capacity arrives later or smaller than a brand needs. The evidence at the time was the process itself and a roadmap for capacity, with no plant yet built. What had been done about it was the shape of the commitment. The brand's step was the Letter of Intent, so the scale-up exposure stayed with Eeden while the brand secured a place in the queue for capacity. The next evidence was a working plant, and Eeden later raised an €18 million Series A to build a demonstration plant. The unacceptable condition is the field a company has to write for itself, because only it knows how much delay its buyers will tolerate. Eeden reports that the pitch helped it sign a major Letter of Intent with a global brand. That result is company-reported. It sits on the buyer side, it came before any plant existed and the brand is unnamed. Our reading is that a buyer committed once its exposure had a size and an owner. The case shows nothing about how lenders priced the same project.
The row also kept one field open, and that is deliberate. FOAK contains genuine unknowns, and hiding them makes diligence harder because the investor then has to uncover both the uncertainty and the team’s view of it.
Different capital providers need the same register at different depths
A buyer cares about delivery, specification and operational consequence. Equity investors care about cost, future funding and value creation. Lenders focus heavily on completion, repayment and protections. Insurers need loss scenarios and controls, and if a risk cannot be described well enough for an insurer to underwrite, the team has probably not defined it well enough for a lender either. Regulators apply statutory tests that may overlap only partly with those financial questions.
The underlying risk register should stay common. One item in it can support several parts of the case. Pilot data may support the technical and risk accounts, and a signed offtake may support the commercial and capital accounts, depending on its actual terms. The same evidence can serve several readers as long as no reader is asked to let it prove more than it can. The buyer pack, equity deck and lender information memorandum can then show different subsets and depths without changing the facts. That prevents the drift in which a project becomes low risk for lenders, technically proven for buyers and commercially certain for equity investors because each audience received a different narrative. The register also has a timetable. Carlota Ochoa Neven Du Mont of the climate fund Extantia Capital told us in 2024 that a deal usually only falls apart after the term sheet if the founders were not open earlier. The investor interviews on how a fund decides after the pitch cover that point. The open rows belong in the first conversation.
When a project needs an equity deck and a lender information memorandum drawn from one risk register, our investor storytelling work builds each at the depth its reader needs. The figures come from the company's own finance team.
The risk case is one of six
A first commercial project has to make six connected cases, which Brighter Future's FOAK Story System names as technology, commercial, project, risk, capital and scale. The technology case shows what has run, at what scale and under which conditions. The commercial case shows who needs the output enough to pay for it. The project case covers the site, inputs, permits, builder, host integration and operator. The risk case is the register this article describes. The capital case explains why each exposure belongs with a particular provider at this stage. The scale case shows what project one proves for project two. Separating them shows which case is strong and which is weak. A project can have a strong technology case and a weak commercial case, or real demand and no financeable structure.
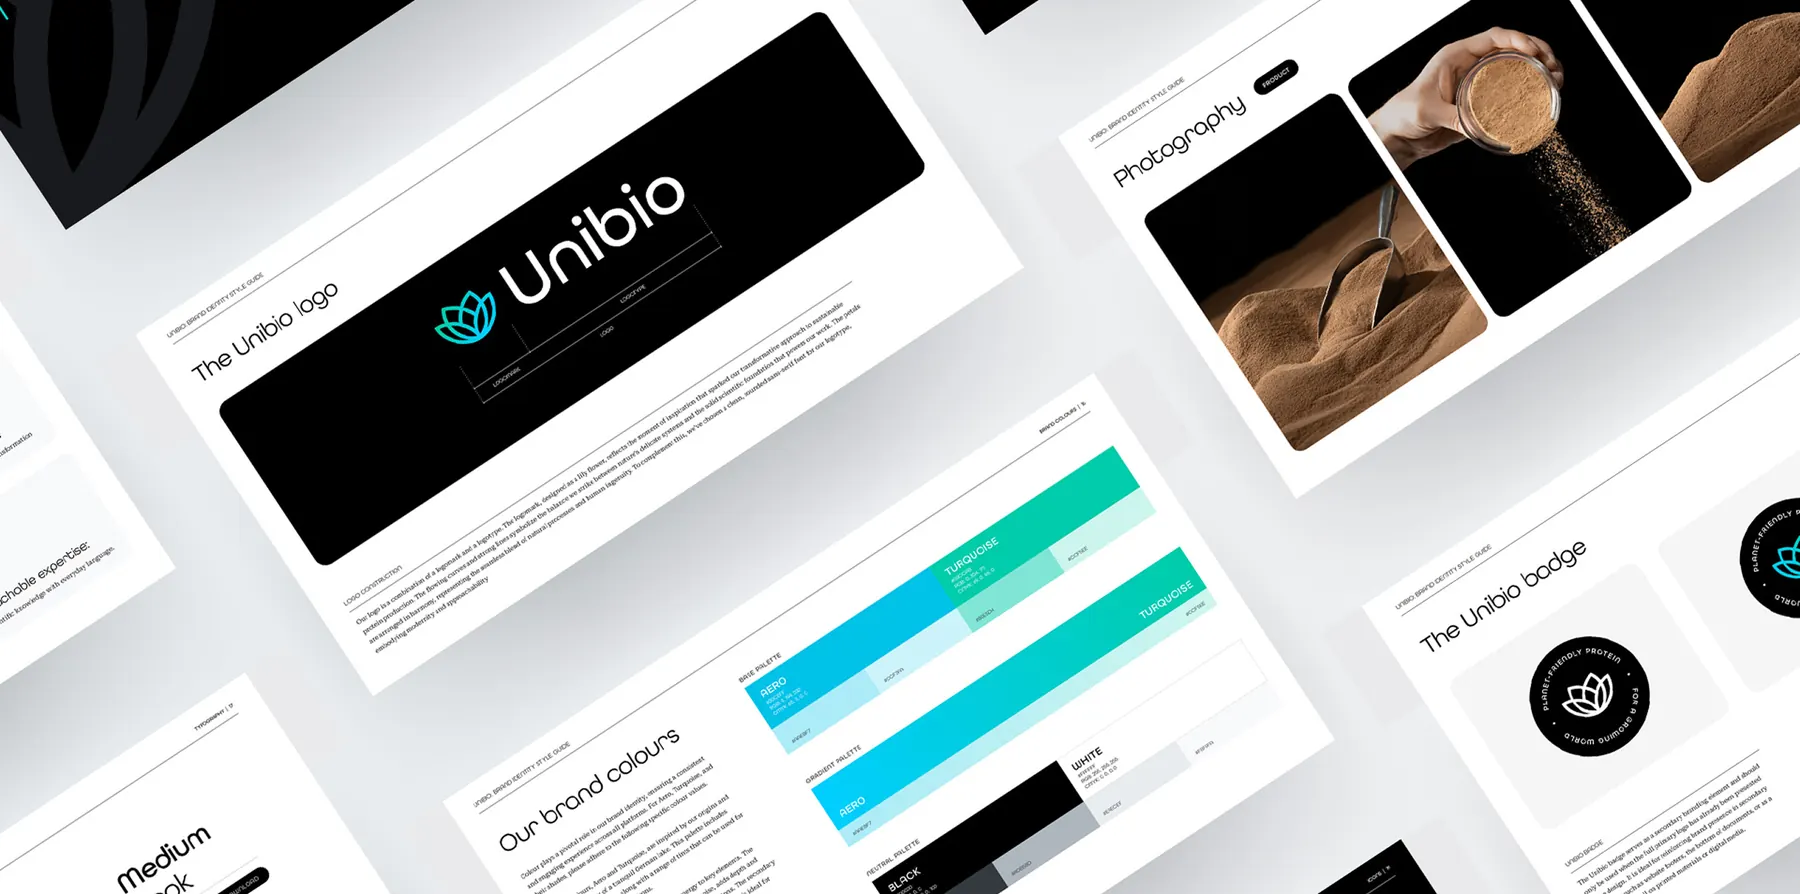
The order of the cases matters too. A FOAK narrative can move from the changed world that makes the output matter, to the buyer's need, the product, the technology and the evidence already demonstrated, and then to the project, the risk, the capital and the scale. The pilot sits in that sequence as one exhibit of evidence, and the four cases after it are new work it was never designed to carry. Our work with Unibio shows the order in practice. Unibio uses gas fermentation to make protein for animal feed, and a company built on a process like this can easily lead with the process. Feed producers buy protein. We repositioned the company around the protein product, with the technology as the evidence behind it, under the line “Lead with protein. Let the technology prove it.” The commercial case went first for the buyer, and the technology case moved into the role of proof.
To find the weak case, score each one on clarity and substance. Clarity asks whether a relevant reader can follow it. Substance asks whether enough evidence or structure stands behind it. A case that is clear and thin needs project work, and polish will not strengthen it. A weak commercial case sends the team closer to buyers, a weak capital case needs finance specialists and a vague risk case needs its exposures broken apart. A quick test on existing materials is to mark every claim in the current deck as pilot evidence, project evidence or assumption. Where project evidence runs thin, that gap is the next quarter's workstream.
Delete the word “de-risked”
A useful final edit is to remove the word “de-risked” from the project materials and see what remains. The reader should still be able to tell what has been demonstrated directly, where adjacent evidence is being used, what a contract or guarantee actually changes, which exposure remains open and who carries it. If those answers disappear with one adjective, the material was relying on reassurance where the reader needed a risk account, and the missing work belongs in the register before it belongs in the presentation.
Brighter Future will help a project make uncertainty legible. We will not turn an unresolved exposure green because the slide looks cleaner that way.
Sources and further reading
- FOAK financing and development approaches, US Department of Energy, 2024
- Anthony Chow, Agronomics, investor interview, June 2024
- Nick Lyth, Green Angel Ventures, investor interview, May 2024
- Eeden case study
- Unibio case study
- What 16 Investor Interviews Teach Founders About the Decision After the Pitch
- What Is FOAK in Climate Tech?
- Why Are FOAK Climate Projects Hard to Finance?
- Why Nobody Wants to Become the Precedent
Tell us what needs to move.
Bring the brief if it is clear. If it is unclear, tell us where the work is stuck.
Bring us the problem